Life Insurance Premium Financing Explained
Borrowing can change how premiums are paid. It does not remove the cost of insurance or the need to repay the debt.
Life insurance premium financing uses a loan from an outside lender to fund some or all of a policy’s premiums. The policy and the loan have separate terms. The borrower must meet the loan obligations even if the policy performs differently from the original illustration.
Strategies are evaluated in coordination with Estate Attorneys, CPAs, and Lending Institutions
What Is Premium Financing?
Premium financing is a strategy that allows a qualified individual to fund life insurance premiums using external capital rather than liquidating existing assets.
Instead of repositioning capital from a business, real estate portfolio, or investment account, a financing structure is introduced to preserve the integrity of the balance sheet. The objective is not to avoid commitment it is to maintain capital efficiency while solving a liquidity need.
Key Clarification: Premium financing is not a product. It is a structure.
Start with the insurance need
A family may want insurance to address a future estate cash need while much of its wealth remains in a business or property. Paying large premiums directly could compete with other uses for available funds.
That can be a reason to compare financing with direct payment. It is not, by itself, a reason to borrow. A valuable business is not the same as cash available to pay interest or meet a lender’s request.
Establish whether the coverage is appropriate first. Then ask how it could be funded under both expected and less favorable conditions.
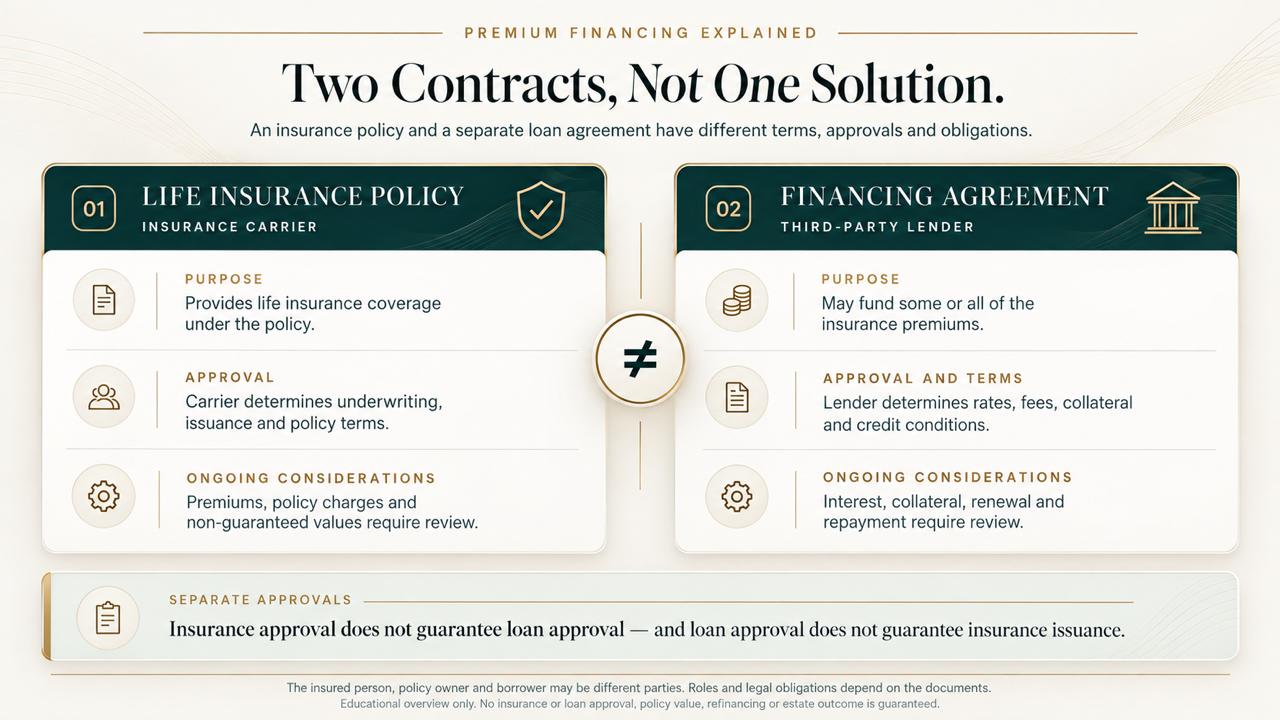
Two contracts, not one solution
| Life insurance policy | Premium-finance loan |
What it does | Provides coverage under the insurance contract. | Funds insurance premiums with borrowed money. |
Who sets the terms | The insurance carrier. | The lender. |
What needs attention | Premiums, benefits, charges and any cash values. | Interest, fees, collateral, maturity and repayment. |
What it does not establish | Approval or renewal of a loan. | Approval of coverage or guaranteed policy results. |
A premium-finance loan is also different from a policy loan, which is borrowing against available cash value under a policy’s own terms. The two should not be used interchangeably in a proposal.
How an arrangement generally works
The policy owner applies for coverage. If financing is being considered, the borrower also seeks credit approval. These may be different people or entities; the legal structure and authority need to be clear.
If both applications are approved and the required documents are completed, loan funds are used for the agreed premiums. The lender may require rights in the policy as security, known as a collateral assignment, along with other eligible assets.
The borrower remains responsible for the required payments and loan conditions. The insurer remains responsible for the policy under its contract. One approval does not substitute for the other.
This is not a loan that directly pays an estate-tax bill. It funds premiums for insurance arranged while the insured is alive.
What still requires cash and attention?
Interest and fees
Find out what must be paid from current resources and what, if anything, the lender permits to be added to the balance. Adding interest to a loan does not eliminate that cost. Review when the rate can change and how a higher rate would affect required payments.
Collateral
Collateral is property pledged to secure a loan. Policy value may not cover the lender’s full requirement, and assets outside the policy may be needed.
If accepted collateral values fall, the loan terms may require additional assets or a repayment. Failing to meet those terms can put pledged assets at risk. Ask what the lender counts, how it values each asset and how much time is allowed to respond.
Underwriting and loan terms
The carrier evaluates the insurance application; the lender evaluates the borrower and security. Actual requirements, approvals and terms vary. Wealth alone does not establish eligibility.
Read the maturity date, renewal conditions, reporting duties and consequences of a breach. The insurance may be intended for a much longer period than the lender has committed to provide credit.
Decide how the debt could end before it begins
An exit strategy identifies how and when the loan could be repaid. A future asset sale, available funds or policy value might be considered, but each needs its own assumptions and fallback.
Refinancing requires another credit decision. It should not be treated as certain. Nor should death be assumed to occur before repayment is due. Requirements differ among lenders.
If policy value is proposed as a source, establish what is actually available after charges and what using it would do to coverage. Do not count projected cash value as guaranteed repayment money.
Ask one practical question: What would we do if our preferred repayment source were unavailable?
Financing versus paying premiums directly
Direct payment uses current resources for premiums without adding a premium-finance loan. It may be simpler, but it still requires an affordable policy and a plan for future premiums.
Financing can reduce the amount initially paid toward premiums from those resources. In exchange, it adds debt costs, lender requirements and repayment risk. A fair comparison includes both the cash retained and the obligations added—not just the first year’s outlay.
Your advisors should also consider whether existing coverage or a different funding approach addresses the original need without new borrowing.
When financing may not fit
Be cautious if the arrangement would use cash needed for other obligations, if a collateral request would be difficult to meet, or if repayment depends on optimistic values and repeated loan renewals.
It may also be the wrong approach if the insurance need is unclear, you prefer not to borrow, or the cost and administration outweigh the potential benefit. A less complex arrangement can be the better choice.
Review does not stop at implementation
Before proceeding, agree who will track loan dates, rates, collateral and policy information. Ask for current figures when assumptions change, rather than relying indefinitely on the original proposal.
SPF does not promise an annual monitoring service through this page. Any ongoing work needs a defined scope and responsible parties.
Put the financing question in context
Marc Setton brings an insurance-focused perspective to estate-liquidity discussions alongside your existing advisors. Legal structure, tax treatment and investment decisions remain with the appropriate professionals.
Marc does not charge a separate planning or advisory fee for this work. He is compensated when an insurance transaction is implemented, under the applicable insurance compensation arrangement.